

Do I Need Life Insurance?
Short Answer
It's a question that only you can really answer.
Ask yourself - Would your family be financially stable if you weren't around anymore, or if you were seriously ill or injured?
It's not an easy question to answer, but it matters, because things can change fast when you're not around.
of us go about our week without ever thinking about illness, injury, or death. It's just not something we plan for.
Then suddenly it hits hard.
It's happened to someone close to you.
It stops feeling distant and becomes a real case.
That's usually when people start asking whether they need cover. So let's talk through it properly.
Firstly, Let Me Be Real With You...
Life insurance isn't for everyone, and I'm not going to pretend otherwise.
Some people genuinely don't need it right now.
If you've got a strong base of assets, little or no debt, and nobody relying on your income, it might not be the priority it is for others.
But for most Aussies, life's not that simple. Most of us have a mortgage, (or pay rent) a household that runs on one or two incomes, and people who'd be in real trouble if either of those disappeared.
So the honest answer isn't yes or no. It depends on the impact you'd leave behind.
Ask Yourself These Questions
Forget the jargon for a second. These are the questions I ask most people, and they'll tell you most of what you need to know.
If I have a serious injury or illness & I'm off work how long could we cover the mortgage, debts and bills?
One or Two months? Maybe a little longer?
What's the shortfall to cover everything, and would you need to take out borrow funds or loans?
Most households can absorb a short shock. Far fewer can absorb one that drags on.
If I passed away what do I leave my family behind with?
This is the one people find uncomfortable, which is exactly why it's worth sitting with.
How long would that last for?
What pressure would that cause my family?
Do I have loans? Who takes care of it?
Debts don't come with you, but they can get left behind for your loved ones
A guarantee can land on a partner, a co-borrower, or your estate. Somebody ends up holding it.
Do my children, partner or dependants rely on my income?
Children are the obvious case, but dependants can also be:
The more people who rely on you, and the longer they'd rely on you, the bigger the gap your income leaves. If you answered yes to any of those and don't have a plan behind it, that's a gap worth looking at.
When People Usually Start Considering Life or Income Protection
Almost nobody wakes up and decides today's the day. It's nearly always triggered by something new in life. Tick anything that sounds like you.


Tick the ones that sound like you - your answers shape what comes next.
Who Needs Life Insurance?Breaks each of these down, including the types of cover that tend to suit them.
What If You Decide You Don't Need Cover?
Choosing not to take out cover doesn't automatically create problems.
Plenty of Aussies are comfortably uninsured, and for some of them that's a perfectly reasonable call.
It's an extra cost, and at certain points in life it's fair to decide it isn't worth it.
But it's worth at least understanding the exposure you're carrying, so you can make the call on whether you're willing to take on the risk, and if so, at what cost.
Who Carries The Most Exposure


Losing that income can mean missed repayments, a lower standard of living, and savings built up over years being drawn down fast.
No sick leave. No annual leave. An extended period unable to work can stall your personal finances and your business at the same time.
If something happened to you, the pressure to provide for your children long-term falls to family or friends. People who may not be in a position to carry it.
Look, I know it's an easy one to push down the list.
okay for how long - a month, or a mortgage?
Right until the exact moment it isn't.
With what income, while figuring it out?
But sit with it for a second.
If your house burnt down tomorrow and you had no home insurance, would you genuinely be alright?
If you wrote the car off and it wasn't covered?
How would you pay out what's left on the car loan, or the remaining home loan, at the same time as rebuilding?
Most of us wouldn't take that risk on.
That's why we insure them without really debating it.
Your income and your life are the same question, they're just harder to picture, because there's nothing sitting in the driveway to look at.
The One Most People Overlook Your Health
This is the part that always gets missed, and it matters more than most people realise.
Life insurance & Income protection isn't guaranteed. You have to be accepted for it - and as we get older, more things tend to go wrong.
What tends to show up over time


Each one on its own is common. It's the accumulation that changes your options.
What tends to show up over time

A higher premium for the same cover.

Certain conditions simply aren't covered.

Cover comes with added conditions attached.
Cover is generally easier to arrange while you're fit and healthy than once health issues have shown up.
That's not a scare tactic, it's just how underwriting works.
The point is that "I'll sort it out later" carries a risk most people don't factor in.
If you're already covered, it's still worth reviewing.
Can I Actually Afford It?
This is the question I get asked most, and it's a fair one.
Cover can be more affordable than people expect, and there's usually more than one way to make it work.

Some cover can be funded through your super balance rather than out of your household cash flow, which changes what it costs you week to week. Some is better held outside super. There are trade-offs either way.

Not everyone needs to insure everything. Some people choose to cover the essentials, like the mortgage and the years their children are dependent, rather than the full picture. A smaller policy in place beats a perfect one you never took out.

Life, TPD, trauma and income protection do different jobs and cost different amounts. If budget is tight, it's worth working out which risk would hurt your household most and starting there.
Not sure what level of cover fits?
Work it out with our calculator.Frequently Asked Questions
Do I need life insurance if I'm single?

It depends on what you're responsible for. Without dependants, a large life cover policy is often less critical. But a mortgage, personal debts or ageing parents who rely on you can still create a need. For a lot of single Australians, income protection is more relevant than life cover, because the bigger risk is losing the ability to earn.
Do I need life insurance if I already have cover through super?
Default super cover is a starting point, not a plan. It's based on population averages rather than your circumstances, and it's often well short of what a household with a mortgage or children would actually need. It's worth checking what your fund gives you before assuming it's enough.
Life insurance through superIs life insurance worth it when you're young?
It can be, if you have financial responsibilities. A mortgage, debts, or people who depend on you. Premiums are generally lower when you're younger and healthier, and as covered above, eligibility can narrow if your health changes later.
Do I need life insurance if I don't have children?
Possibly. Children aren't the only reason people hold cover. A partner who shares your debts, a mortgage, personal loans or a business can all create obligations that wouldn't disappear without you. If none of those apply, it may be less of a priority.
How do I know how much cover I need?
It usually comes back to three things: what you owe, what your household spends, and how long they'd need the money for.
How much life insurance do I need?How Much Life Insurance Do I Need?
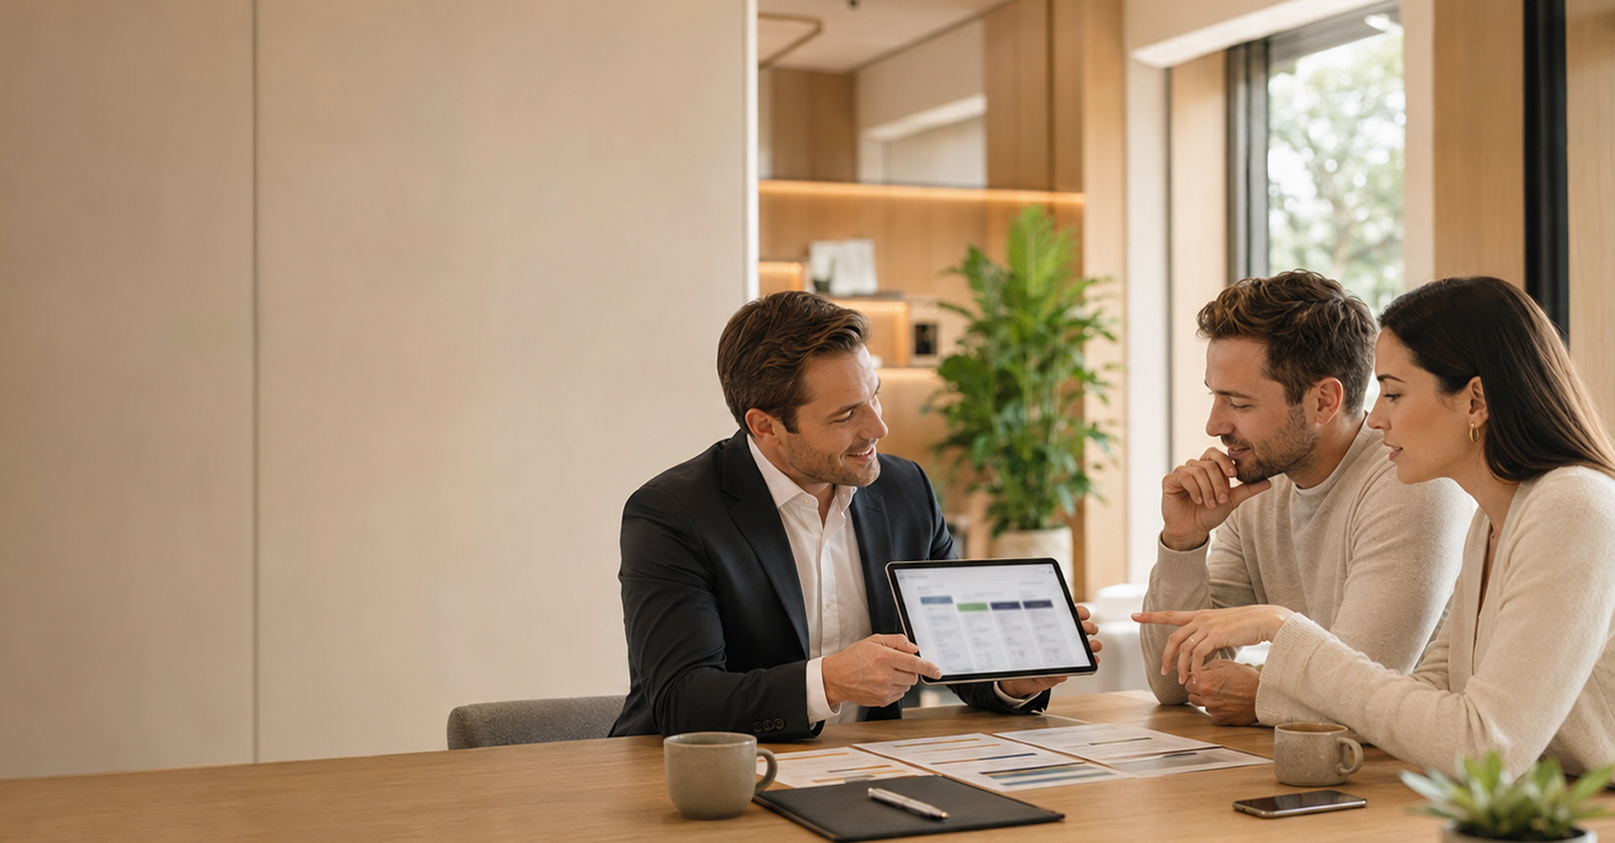
If working through those questions has you leaning towards yes, the next step is figuring out how much cover fits your situation and what's available to you.
I'm Kenwil Vaz. I've been arranging life insurance for Australians for over [X] years and have placed more than $100 million in cover. My job on a first call is not to sell you a policy. It's to help you work out whether you need one, and what it'd look like if you did.



The information on this page is general advice only. It has been prepared without taking into account your objectives, financial situation or needs. Before acting on it, you should consider whether it's appropriate for you, and read the relevant Product Disclosure Statement and Target Market Determination before deciding whether to acquire a product. Protect Buddy is a Corporate Authorised Representative (CAR No. 1319120) of Nexa Life Solutions Pty Ltd (AFSL 563622).
How Much Life Insurance Do You Actually Need?
A practical guide to calculating the right amount of cover for your situation.
Life Insurance Inside vs Outside Super: What's The Difference?
Understanding where your cover is held and why it matters.
Stepped vs Level Premiums: Which Is Right For You?
How premium structures work and which option saves you more over time.